The Fed, Iran, Oil, and AI
There is so much to cover. I think this will be one of the first FOMC meetings where I will be stuck on a plane, which is an unfortunate bit of scheduling on my part.
The Fed
Today is one of the more “unique” Fed meetings we’ve had. The last press conference highlighted some contentious issues – chiefly Powell not stepping down until the probe was dropped. The probe has been stopped, presumably allowing Powell to step down and clear a path for Warsh. Though, he might be looking for more reassurance that a new probe doesn’t commence once he steps down. That is the “political” portion of the meeting.
It seems incredibly difficult to get a dovish Fed today. Oil is hitting fresh highs. Many chemical and plastic plants in Asia remain in limited operations, having declared force majeure. Diesel, fertilizer, and jet fuel continue to hit the headlines daily, not in a good way. While alternative measures of inflation (like Truflation) are below 2%, they are well off their pre-Iran attack lows.
It is a shame the jobs data doesn’t come out until next week. Last month’s jobs data was “shockingly” good, so it is difficult for the Fed to bet a lot on a “softening” labor market. I think this month’s report will show that last month’s report was an anomaly (as so many have turned out to be) and that the job market is softening, but we don’t have that evidence as the Fed meets today.
No cut. I don’t see any chance of a hike due to the conflict in Iran (Powell should make that clear), and there won’t be a cut until the conflict is resolved and there is clarity on the global energy front.
Look for yields to leak higher, my current target is for 10s to drift towards 4.5%. We have had to move the “midpoint” of our range from 4.25% to 4.4% as not only are we worried about the inability of the Fed to cut, but also Treasuries are just not a “scarce” asset. Market practitioners across the globe need U.S. stocks and U.S. corporate credit. Treasuries are more easily substituted with domestic government debt. It doesn’t mean that Treasuries will not remain important, but they have less relative appeal than they once did. As countries need to spend money to finance defense spending and energy spending (and hopefully ProSec™ style infrastructure spending), there will be more pressure on global bond yields.
Iran
We should get more information as Secretary Hegseth sits for public Congressional hearings.
My current (simplified) take:
- The admin believes the U.S. blockade of the Strait is harming Iran’s economy to the point it has increased leverage on them to come to the table. It is also possible, which would be great, that as the ceasefire holds, other nations help. That is still on the “wishful” thinking side of things, but let’s toss it out there. So, we wait.
- The admin believes that there is some struggle for control in Iran (there is certainly a question of who is exactly in charge and how strong is their grip on power). Presumably, we are watching, waiting, tracking, and trying to influence Iran’s internal battle for control. So, we wait.
- The U.S. is bringing fresh troops and equipment to the region. We may even see some “developmental” weapons deployed to counter the asymmetric warfare that Iran has used (with some degree of success) against us. We repair and rejuvenate our troops and equipment in the region. We are probably not at the apex of our power – estimates are that this might be the case in the next few days, to up to two weeks.
- At that point we might see troops and equipment rotate out. Long haul and more waiting.
- The U.S. launches the strikes and attacks designed to set the regime up for failure. The waiting is over.
My view is that the President is convinced the best (if not the only outcome) is the end of Iran’s nuclear program (full stop) and a big enough shift in the regime so that they are no longer a threat to the region.
Leaving the situation in a state where in a matter of years, we will have to go through it all again, with a likely more dangerous and entrenched foe, is the least favorable way to end this.
The legacy of ending “Revolutionary Iran” would be great for the President (and the world).
The flip side of that is markets are too complacent. Equities in particular seem to continue to price in some form of “TACO” that seems less likely.
How markets wind up, if we are right and we are pursuing this to a greater endgame, depends on damage done in the region. If some version of “real” victory can be achieved with minimal damage done to the region, markets can go off to the races. We can price in a much more interesting Middle East and even start thinking about what rare earths, critical minerals, and other commodities can be found in Iran.
The downside is there is some all-out, “backed into a corner” fight that severely damages energy and infrastructure in the region, making it extremely difficult to avoid a global slowdown.
Oil
This is the first chart I look at every day.
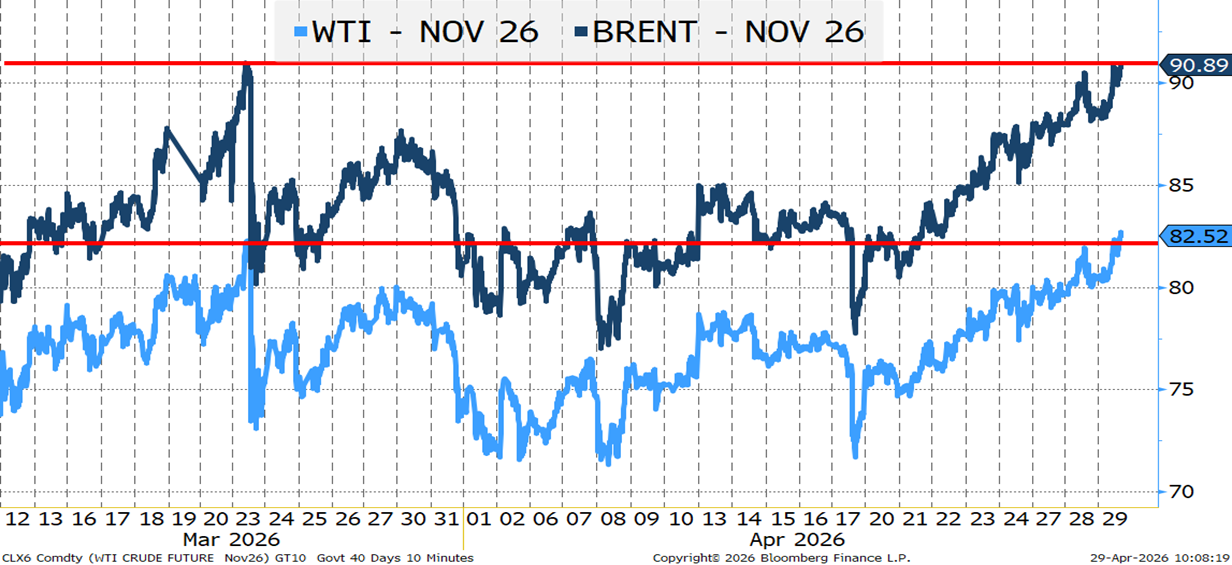
The November contracts for WTI and Brent Crude are basically at their highs since the conflict started. “Comfort” from markets pricing in a swift return to normal should be eroding. This chart will unfortunately be more and more difficult to ignore.
If I am correct on my estimates of the administration’s approach and Iran’s unwillingness to back down, this chart likely gets worse before it gets better.
AI
A Wall Street Journal article about ChatGPT spooked the tech sector yesterday. There were two things that I took as positive:
- The stocks that were hit the most, orbited closest to this product. There was very little of “the baby with the bathwater.” The investment community seems to fully understand that there are a variety of competing products out there. That there has been some “leapfrogging” in terms of what is most talked about today. But, there is also plenty of opportunity to change the narrative with new versions or new products. The “targeted” nature of the sell-off indicates a maturing of the market, which is a positive.
- Over the course of the day, comments from the company, countering the WSJ article, got traction and lessened the damage. That is also quite positive.
The ongoing rally in the sector (especially the semis) has continued even as announcements in China are trying to hype their offerings.
This rally seems to be firmly set on a better foundation than even in the past. As discussed in this weekend’s report – Don’t Mind the War, moving from oversold to overbought (in the fashion we did it) leaves us susceptible to some pullbacks, but I like how the market handled yesterday.
Bottom Line
No help from the Fed.
No help from the Iran conflict.
Be a little cautious on risk and bonds here, even on the AI story, though I really liked how it digested yesterday’s initial larger move lower.